At its
Annual Insights Symposium (AIS) in May 2026, NCCI presented the
State of the Line Report—a comprehensive assessment of the workers compensation (WC) insurance line of business. The results presented in that report reflected the most current data available at the time, including NCCI’s preliminary estimates for Calendar Year (CY) 2025.
This report provides both updated results for 2025 and an early look at 2026.
Key Insights
Final workers compensation private carrier countrywide results:
- CY 2025 net written premium (NWP) decreased from 2024 by 0.2% (staying around $41.6 billion).
- The CY 2025 combined ratio was 90.6%, and the operating gain was 18.2%.
Updated preliminary claim frequency and severity estimates for NCCI states are unchanged from the initial estimates announced at
AIS:
- Accident Year (AY) 2025 claim frequency is still expected to be 2% lower than 2024.
- AY 2025 indemnity claim severity and medical lost-time claim severity are estimated to be 4% higher than 2024.
While still early and subject to revision, preliminary analysis for private carriers through the second quarter of 2026 shows:
- CY 2026 direct written premium (DWP) decreased 0.4%, compared with the first half of 2025.
- The CY 2026 direct loss ratio is 52%, two points higher than the first half of 2025.
- The line is expected to have another strong year with continued underwriting gains in 2026 and a net premium volume like that observed in CY 2025.
Click the image to access the State of the Line: The Latest Results in 2026 snapshot.
2025 in Review
For CY 2025, the final written premium net of reinsurance is $41.6 billion for private carriers. This is unchanged from the NWP estimate presented at
AIS 2026 and represents a 0.2% decrease from 2024.
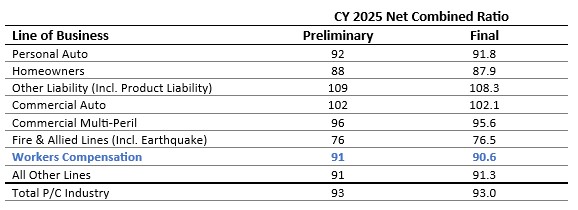
For CY 2025, NCCI previously estimated a WC net combined ratio of 91%. Updated industry data indicates a net combined ratio of 90.6%, a 9.4% underwriting gain. This represents a 4.5-point increase from the prior year, which is primarily attributable to an increase in the loss and underwriting expense ratios.
The CY 2025 combined ratio marks the 12th consecutive year of underwriting gains. The current period of consecutive underwriting gains is unprecedented in terms of both duration and magnitude and is reflective of a prolonged soft market in the underwriting cycle. While the CY 2025 combined ratio is the highest since CY 2016, this result continues to indicate a significant underwriting gain.
The WC investment gain on insurance transactions (IGIT) measures investment performance by comparing investment income allocated to the WC line of business with the corresponding earned premium. At
AIS 2026, the IGIT for CY 2025 was estimated to be 9% of net earned premium. Updated industry data indicates a ratio of 8.8%, which is below the 20-year average of 11.3% but relatively consistent with recent years.
The WC pretax operating gain measures the overall performance of the WC line of business, reflecting both underwriting and investment income. The CY 2025 underwriting gain of 9.4%, combined with the investment gain of 8.8%, resulted in an overall operating gain of 18.2%. This value is similar to the preliminary estimate of 18% shared at
AIS 2026, which was the lowest value since 2016 but remains above the 20-year average of 15.2%.
The table below summarizes the preliminary estimates provided at
AIS 2026 and the final values for CY 2025.
Overall, workers compensation exhibited strong performance in 2025 with a combined ratio below that of the total property and casualty (P/C) industry. The total P/C combined ratio of 93.0% represents the lowest combined ratio for the industry in nearly two decades. The table below summarizes the preliminary estimates provided at
AIS 2026 and the final CY 2025 private carrier combined ratios by line of business.
At
AIS 2026, NCCI shared that WC lost-time claim frequency
declined by 2% in AY 2025, while both indemnity and medical lost-time severity had each
increased by 4% in AY 2025. These figures represented NCCI’s initial estimates based on the latest information available at that time and were denoted as preliminary (p). NCCI’s preliminary estimates are subject to change because the Financial Call data that is initially reported in April of each year is continually validated and analyzed throughout each ratemaking season. Final frequency and severity results are published the following spring after all NCCI filings are submitted. The waterfall graphs below illustrate how updates to various components of the analysis—based on the latest available information—impact the results. This impact is shown as a net change (∆) which will then be broken out by individual component.
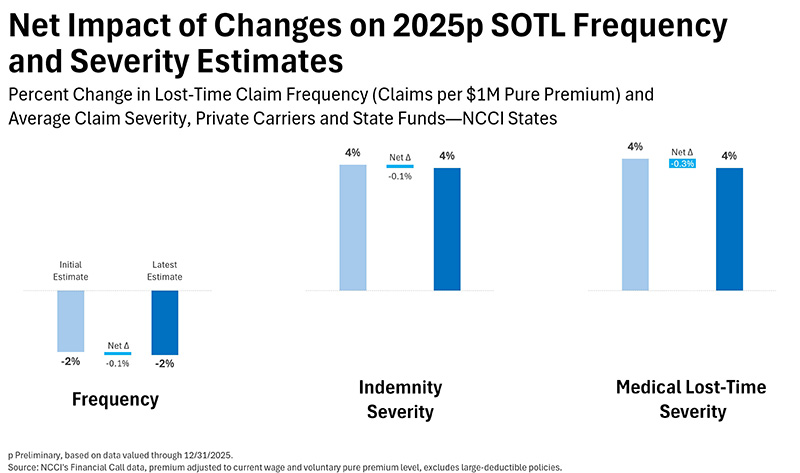
Based on the latest available data and assumptions, NCCI expects the frequency and severity changes from AY 2024 to AY 2025 to be unchanged from the initial estimates―a 2% decrease in frequency and a 4% increase in both indemnity and medical severity, rounded to the nearest percent. At a greater level of precision, the net impact of the updates to the underlying data and assumptions for each metric is currently estimated to be between approximately –0.1% to –0.3%.
For frequency, the largest component change is attributable to the use of updated premium on-level factors underlying each of NCCI’s proposed or approved filings. Those effects are then offset by the combined impact of updated wage inflation assumptions and other data adjustments. There are no explicit premium audit adjustments applied to either AY 2024 or AY 2025 and only a minimal change in the frequency estimate due to updated industry data.
Changes to the underlying industry data—because of carrier data submissions and corrections—have put more upward pressure on the indemnity and medical lost-time severity estimates than on frequency. The largest impacts by component change are coming from general loss emergence and development. Ultimate indemnity and medical severity for AY 2024 have both increased since the prior valuation as of 12/31/2024, putting downward pressure on the change across AY 2024–2025. This effect is more pronounced for medical severity; however, it is partially offset by the impact of other data adjustments, including the application of factors that remove losses associated with medical-only claims to isolate the medical costs of lost-time claims.
2026 in Sight
For the 2026 preliminary analysis of WC results, NCCI used National Association of Insurance Commissioners (NAIC) Quarterly Statement data, which is only available on a direct (of reinsurance) basis. To infer how the quarterly data may develop by year end, a review of the quarterly data alongside year-end direct and net of reinsurance values was performed.
Premium
In the graph below, changes in cumulative DWP by quarter from one calendar year to the next are paired with changes in NWP at year end.
Countrywide, NAIC private carrier DWP decreased 0.4% through the first half of 2026, compared with the first half of 2025. This decrease is like the –0.7% change observed through the first quarter of 2026. Considering the 2026 results to date, the year-end NWP change will likely be a slight decrease, resulting in 2026 NWP just under or similar to the $41.6 billion figure observed in 2025. This estimation is a reasonable possibility, assuming DWP develops similarly to historical patterns and the relationship between direct and net premium holds consistent.
Because premium is calculated as payroll times rate, the combined impact of the changes in those components drives the overall change in premium. NCCI expects the impact of rate/loss cost level changes on premium to decrease in 2026 by about 5%, on average, as a result of recent rate/loss cost filings. Factors contributing to this decrease include the wage-sensitive exposure base (payroll) in WC, as well as declines in lost-time claim frequency and moderate changes in claim severity.
For more information on the modest decreases in bureau level changes over the last several years, please see
Loss Cost and Rate Changes: Will There Be a Turn?
Other factors also contribute to rate changes, such as changes in schedule rating, dividends, rate/loss cost departure, average experience rating modification, deductible credits, or mix of policies. The impact of these factors cannot yet be estimated, but over the last several years these factors combined have put upward pressure on premium.
Further offsetting bureau premium level decreases, payroll through the first half of 2026 increased more than 4.0% over the prior year (sources: US Bureau of Labor Statistics; US Bureau of Economic Analysis; NCCI). With less than 1.0% growth from employment, this increase is mostly driven by a nearly 4.0% increase in wage rate.
Combined Ratio
In analyzing the profitability of the line in 2026, NCCI reviews the countrywide combined ratio results. The combined ratio is the sum of the loss, expense, and dividend ratios. The private carrier direct loss ratio for the first half of 2026 is 52%, which is two points higher than the direct loss ratio observed through the first half of 2025.
In the graph below, we can see a consistent pattern where the loss ratio at year end tends to be slightly lower than the loss ratio at second quarter. For example, at the end of 2025, the direct loss ratio was 48%, about two points lower than the loss ratio through the second quarter. Also notice that the year-end net and direct loss ratios have been similar in recent years.
We cannot predict future outcomes with any certainty, but if we assume similar development in 2026, the net loss ratio will be in a similar range as or slightly higher than the 2025 result.
NAIC Quarterly Statement data does not contain expenses by line of business. Therefore, NCCI makes the additional assumption that WC expense ratios (including dividends) for 2026 are equal to those of 2025. Note that while the expense ratios are not expected to change significantly from year to year, there is the potential for some variability, which is accounted for in this year’s estimate. Based on the range of values in recent years, it seems reasonable that the total CY 2026 expense ratios could deviate from those of 2025 by about one percentage point.
With these assumptions in place, it is reasonable to expect that the 2026 year-end net combined ratio will be similar to that of 2025 and likely range from 91% to 96%, as displayed below. This would result in 13 consecutive years of WC calendar year combined ratios under 100%.
Overall, the workers compensation industry continues to exhibit signs of strong performance in CY 2026.
Join us for
AIS 2027, May 10–12, 2027, where we will present the full-year view of 2026 results.
Notes
This document includes assumptions and projections. As with any prospective analysis, there exists estimation uncertainty in these assumptions and projections. Areas of this analysis subject to estimation uncertainty that could have a material impact on the results include:
- The development of Second Quarter 2026 direct written premium, direct earned premium, and direct incurred loss to year-end values
- The relationship between direct and net business
- The expected expense ratios
- The impact of changes to laws and regulations
This article is provided solely as a reference tool to be used for informational purposes only. The information in this article shall not be construed or interpreted as providing legal or any other advice. Use of this article for any purpose other than as set forth herein is strictly prohibited.